You’re losing 10 to 20 percent of what you make every year to four financial leaks you never see: taxes, interest, investment fees, and insurance you’re overpaying for.
And every dollar you stop losing is worth about a dollar fifty you’d have to go out and earn, because the dollar you earn gets taxed and the dollar you stop losing doesn’t.
So before you work harder, and before you take on more risk, let me show you where yours are going.
What’s the third option nobody sells?
Every piece of financial advice starts in the same place. Make more, or spend less.
There’s a third option, and it’s the one nobody sells, because there’s no product attached.
Keep more of what you already make.
This isn’t budgeting. Budgeting is about the money you spend on purpose. This is about the money leaving without a decision behind it.
You already earned it. You already took the risk. It’s just not reaching you.
Nobody tries to fix a leaking bucket by pouring faster. You’d look at the holes first. Everyone knows that.
And then with money, we pour faster for 30 years and call it a plan.
Why does a recovered dollar beat an earned dollar?
Here’s the math, and it’s the reason I’ve invested my career here.
Find $1,000 a year you were losing, and plug it. That $1,000 is yours.
Now instead, go out and earn another $1,000. You don’t get $1,000. You get what’s left after tax.
To put $1,000 in your pocket, you have to earn something like $1,500.
And the recovered version took no extra hours, no extra risk, and nobody had to say yes to you.
No investment on earth pays like that, because it’s not an investment. It’s money that was already yours, arriving where it was supposed to go.
There are four places it goes instead. I call them the four I’s.
The first leak: how does the IRS take more than it’s owed?
Nobody sends you a bill for the money you’re losing here. No notice, no late fee, no phone call. It just quietly doesn’t show up, year after year, and you assume that’s normal.
This is probably the largest expense of your life, and the least examined one.
The problem isn’t your accountant. Most accountants are historians. They record what happened. They keep you compliant, and that’s a great thing. It’s just not usually tax savings.
A strategist changes what happens. Those are two different jobs, and most people only hired one.
The tell is simple. If you meet about taxes in March or April, about the previous year, you’re reporting. If you meet in October, about the year you’re currently in, you’re planning. That’s where overpaid tax stops.
Where it leaks: the wrong entity, which is just how your business is set up for taxes, deductions never claimed, and the biggest one, deferring tax and calling it saving tax. Deferral moves the bill to a year when you don’t know the rate. That’s not a strategy, that’s a bet.
One of our Multiplier Members, Brad, bought a home but wasn’t ready to move in just yet. So we asked him if he’d Airbnb it until he sold his other home and moved.
When the answer was yes, he qualified for the short-term rental loophole, which is just a rule that lets the write-offs from a rental with short guest stays, one you actively run yourself, offset your regular income.
Cost segregation, which means breaking a building into parts so the pieces that wear out fast get written off in years instead of decades, plus 100 percent bonus depreciation, put hundreds of thousands back into his life.
That came from our tax strategist. Not from his CPA, who simply files, year to year.
The second leak: which loans are costing you the most?
Not whether you have loans. Whether the loans you have are efficient.
Most people attack the loan with the biggest balance or the highest rate. Both are usually wrong.
Take the balance and divide it by the monthly payment. That’s the Cash Flow Index.
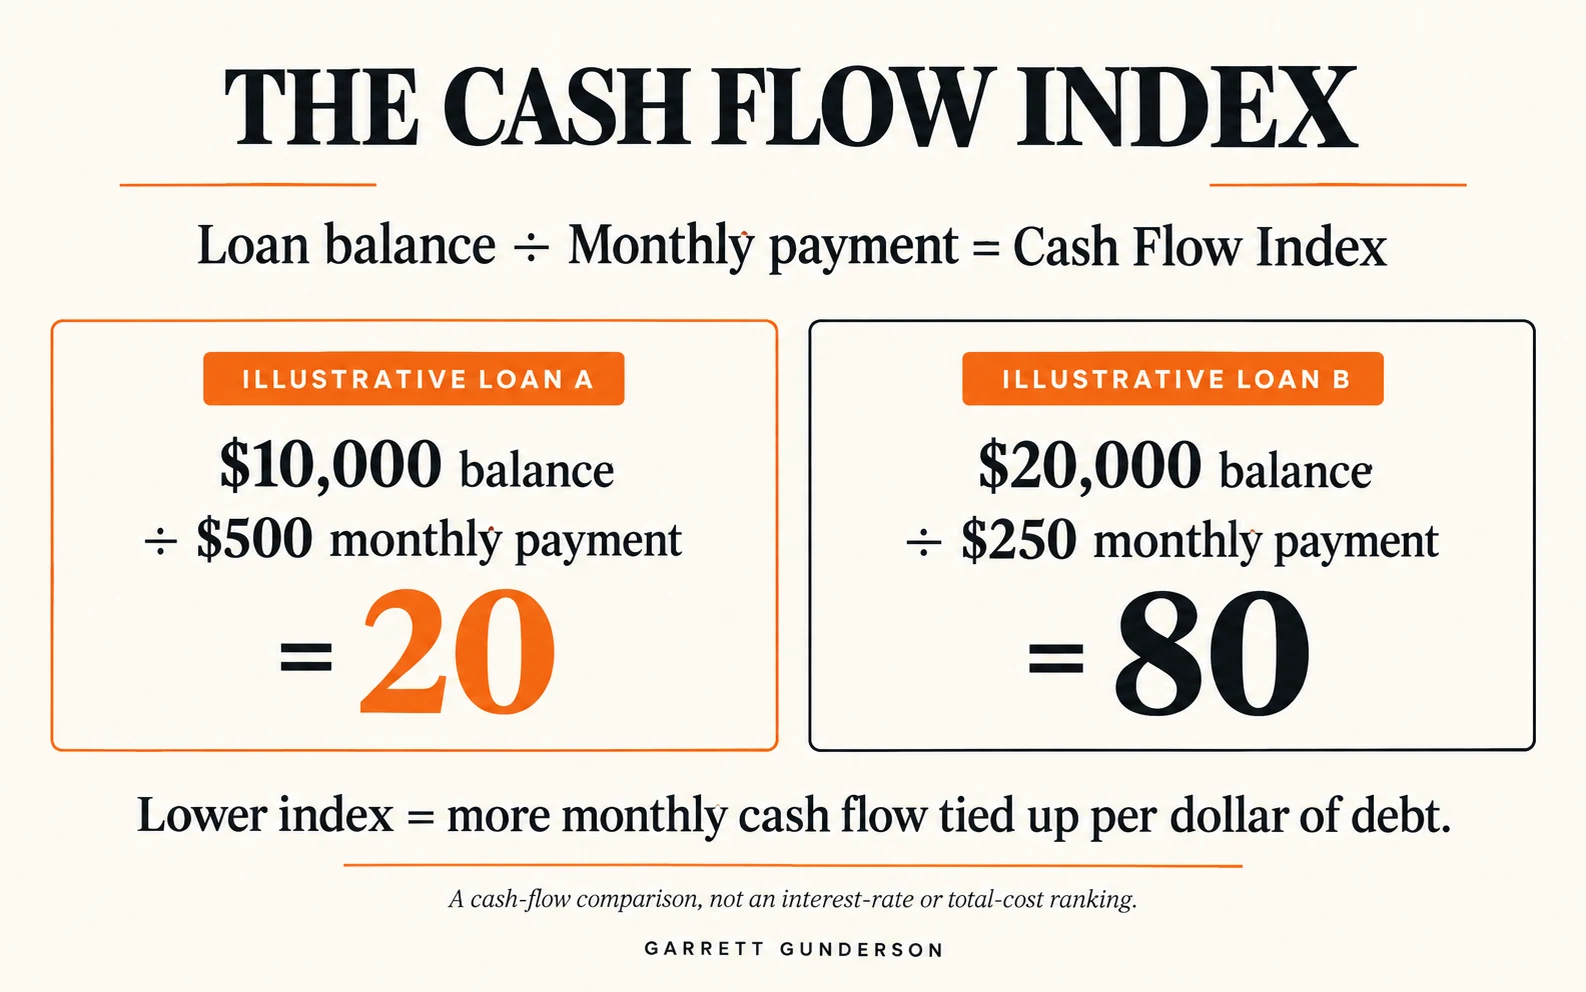
Under 50, that loan is eating a lot of cash flow for a small balance, and it’s the one to kill first. Over 100, leave it alone.
Then there are the three R’s: refinance, renegotiate, reallocate. Most people have never once asked a lender for a better rate. Some of them would say yes.
Or maybe you have underperforming assets that don’t earn what you pay. Pay the loan off and guarantee the savings.
The third leak: what do investment fees really cost?
The quietest one, and the largest over a lifetime.
One percent. People hear it and nod, because 1 percent sounds like a rounding error.
Run it out over a working lifetime and it takes roughly a quarter of everything you build. Not 1 percent of your wealth. About 25 percent of it.
And here’s what makes it a leak rather than a cost: you never saw it. It doesn’t arrive as a bill. It’s taken before the number prints on your statement.
Then add the layers. The fund has a fee. The person managing the money has a fee. Maybe a platform fee under both.
None of it is fraud. It’s just nobody’s job to add it up for you.
One percent sounds like a tip. Compounded over 40 years, it’s a partner. A silent partner who took a quarter of the business, never came to a meeting, and never put in a dollar.
The move: pull your statements and add up every fee layer, the fund’s, the manager’s, the platform’s, as one number. Then ask what you’re getting for it.
The fourth leak: where is your insurance backwards?
Two failures here, and they look like opposites. Most people have both at once.
Overpaying for things that wouldn’t ruin you, and underinsured against the things that would.
The rule: if it happens and you can write the check and sleep, don’t insure it. If it happens and it derails your life, transfer that risk and don’t negotiate on it.
Raise the deductible on what you can absorb. Buy real coverage on what you can’t.
And look for duplication: coverage through work, through a card, through an association, all overlapping. You can pay three times for one protection and still be exposed where it counts.
This reminds me of a time I was speaking in Minneapolis. I remember it clearly because I came from 82-degree weather in Cancun to 22 below, before wind chill, in Minneapolis.
As I walked on stage to speak to the 400 participants, someone immediately raised their hand. I checked my zipper. Ok, there. Why would they already raise their hand?
They didn’t put it down. Two paragraphs in, I finally acknowledged it. It was a CPA, married to the doctor who’d signed up for our program earlier that year.
The CPA said we’d told them they would shave a third of the time off their 10-year plan to pay off loans, and that wasn’t true.
Now I was considering going outside in the cold. But after the long pause, and it seemed like forever, the CPA said they’d be debt free in 3 years and 3 months. I think they even quoted the number of hours and minutes. It was precise.
We restructured loans. We saved on taxes by setting up a different type of election with the LLC, which is just choosing how the IRS treats the company for taxes. We took underperforming savings that were losing to inflation and paid off the higher interest rates, like the student loans.
It was a collection of all four I’s that saved years.
How much do the four financial leaks add up to?
None of these four are dramatic. That’s exactly why they last for decades.
- A few points on taxes.
- A few on interest.
- A quarter of the investment growth.
- A recurring premium overpayment.
Put them together and 10 to 20 percent of what you earn is a conservative estimate.
And remember the multiplier: recovered dollars are worth about a dollar fifty in earned income. So a 10 percent recovery is closer to a 15 percent raise, without asking anyone for it.
This is what I mean by financial fitness. Plug the leaks before you chase the returns.
You can’t out-earn inefficiency. People try their whole lives, and it never works.
I had a dentist with four practices who was paying $15,000 more per month than necessary. Between inefficient loans and overpaid tax, that was more money than he was personally taking home at the time.
Most of it: borrowing from assets instead of taking a business loan from the bank. Refinancing. Improving credit, and with it, the rates.
Setting up the right company and paying him with two checks instead of one, because salary versus distributions can save up to 15.3 percent on every dollar. Oh, and using cost segregation on the buildings he owned the practices in.
Not a one-time $180,000. Every single year. To the bottom line. Spendable cash, not revenue.
So here’s my question. Do you know your number, the one that’s leaving every year without a decision behind it?
Get your leaks found for you
If you’d like help finding your number, my team does a free discovery session for business owners doing at least $350,000 in revenue.
We simply ask questions and show you where the leaks and quick wins are. Nobody sells you anything on the first call.
If we can help, we set up a separate call to share your personalized Report of Findings: what it looks like to hire our team of CPAs, tax strategists, insurance and investment experts.
Oh, and we usually pay for ourselves with the savings from the four I’s.
In prosperity,
Garrett Gunderson
Frequently Asked Questions
What are the four I’s?
The four places money leaks without a decision behind it: the IRS (overpaid tax), Interest (inefficient loans), Investment fees (layered percentages you never see), and Insurance (overpaying for small risks while underinsured against big ones).
What is the Cash Flow Index?
Divide a loan’s balance by its monthly payment. A low number means the loan eats a lot of cash flow for a small balance, which makes it the one to pay off first. It beats attacking the biggest balance or the highest rate.
How much do investment fees cost over a lifetime?
A 1 percent annual fee, compounded over a working lifetime, consumes roughly 25 percent of what you would have built. Layered fees, the fund’s, the manager’s, the platform’s, push it higher.
What is cost segregation?
Breaking a building into its parts so the pieces that wear out fast get written off over a few years instead of decades. Paired with 100 percent bonus depreciation, it can move six figures of write-offs into a single year.
Is deferring taxes the same as saving taxes?
No. Deferral moves the bill to a future year at a rate a future Congress decides. Savings removes the bill. Most plans sold as tax savings are deferral wearing the wrong name.